Incapacity Documents for Parents

Young parents who are relieved that they have their incapacity documents in place.

That’s something we regularly help our clients with. It’s not something you should try to handle on your own. You want to work with an attorney experienced in trusts and in naming trusts as beneficiaries to be sure everything is set up correctly.

As a parent, are your children truly protected if you become incapacitated? While it’s an unpleasant thought, there may come a time when you’re unable to make decisions for yourself due to an accident, illness, or medical condition. That’s why incapacity planning is such an important part of a comprehensive estate plan. Having the proper legal documents in place is essential for parents.

Now, let’s walk through the key legal documents involved in incapacity planning, what happens if you don’t have them, and how to make the best decisions to protect yourself, your assets, your children, and your legacy.

Understanding Incapacity
Incapacity refers to a person’s inability to make rational decisions or properly care for themselves due to mental or physical impairments. It can strike anyone at any age through illness, injury, or age-related conditions. Recognizing the potential for incapacity and planning ahead is crucial for protecting your wellbeing and assets.
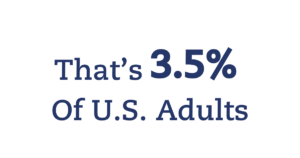
A study done by U.S. Department of Health and Human Services alarmingly found that 9 million Americans over the age of 18 become incapacitated due to illness or injury each year.
9 million Americans over the age of 18 become incapacitated due to illness or injury each year.
When was the last time you thought about the possibility of becoming incapacitated? Do you know what can lead to incapacitation?

Mental Incapacity

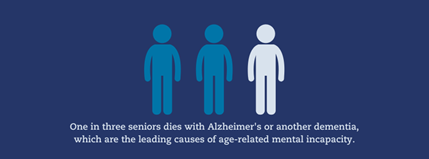
Mental incapacity involves a deterioration of cognitive abilities that compromises decision-making capacity. Conditions like Alzheimer’s disease, dementia, severe mental illness, or brain injuries can rob individuals of the faculties needed to manage their own affairs responsibly. As mental decline progresses, even basic tasks like paying bills or making healthcare decisions can become impossible without assistance.
In a 2024 statistical resource, The Alzheimer’s Association stated that millions for Americans Are living with Alzheimer’s or other dementias.

Physical Incapacity

Physical incapacity results from medical conditions, injuries or disabilities that leave someone unable to physically care for themselves or communicate their wishes. Debilitating diseases like Parkinson’s, stroke, or end-stage conditions can render a person physically helpless and dependent on others for daily care. Severe injuries from events like car accidents can also result in temporary or permanent physical incapacities.

To learn about the leading causes of disability, checkout this article from MedicineNet.

Age-Related Incapacity

While not inevitable, the risk of incapacity increases substantially as we age. The natural cognitive decline that often accompanies aging can impair decision-making abilities over time. Physically, the frailties of advanced age make elderly individuals more susceptible to falls, illness or other conditions that impact self-sufficiency.

Preparing for potential age-related incapacities through proper legal planning gives you control over your latter life care. The same 2024 statistical resource stated that more than 11 million Americans provide unpaid care for a family member or friend with dementia. If you plan ahead you could provide funds for this type of care if necessary.
The Importance of Incapacity Planning

The consequences of incapacity can be devastating if you have not established the proper legal arrangements in advance. Without documented instructions, you could be subjected to costly court guardianship proceedings where a stranger makes decisions about your care and assets. Proper incapacity planning allows you to nominate people you trust to carry out your wishes if you become incapacitated.

Planning safeguards your independence, dignity, and finances during a vulnerable time of life.

By understanding the realities of incapacity and taking proactive legal steps, you ensure your affairs will be managed properly by those you trust most if you can no longer make decisions for yourself. Incapacity planning provides invaluable peace of mind that your future care aligns with your values and priorities.

Legal Documents for Incapacity Planning

Durable Power of Attorney for Finances

One of the most crucial legal documents for incapacity planning is a durable power of attorney (POA) for finances. This powerful instrument allows you to nominate someone you trust to manage your financial affairs if you become incapacitated and unable to make decisions for yourself.

With a durable POA, you (the “principal”) grant legal authority to an agent (also called an “attorney-in-fact”) to act on your behalf in financial matters. This can include tasks like paying bills, managing investments, filing taxes, buying/selling property, and handling banking transactions.
The “durable” provision ensures the POA remains valid if you become mentally incapacitated, unlike a regular POA which terminates upon incapacity. This key distinction provides continuity in managing your finances during periods of incapacitation.

Legal Documents for Healthcare and End-of-Life Decisions

Health Care Proxy

Alongside the durable power of attorney for finances, Healthcare Proxy is another critical component of an incapacity plan. This legal document allows you to name someone you trust as your agent to make medical decisions on your behalf if you become incapacitated and unable to communicate your wishes.
Your appointed healthcare agent can consult with doctors, review medical records, authorize, or deny treatments and procedures, arrange for home healthcare, and ultimately make choices aligned with your values and preferences.
Choosing the right person as your healthcare proxy is vital, as they may need to make life-or-death choices for you. Many people select a spouse, adult child, parent, or very close friend who understands their beliefs about medical care. Discussing your wishes openly and ensuring they can uphold that responsibility is advisable.

Living Will

A Living Will, also called an advance healthcare directive, works alongside your Healthcare Proxy by documenting your end-of-life preferences. Within this legal instrument, you can specify your desires regarding life-sustaining measures like:

  • Resuscitation if you stop breathing or your heart stops
  • Use of a ventilator for breathing assistance
  • Tube feeding for artificial nutrition
  • Palliative or hospice care
A Living Will provides clear instructions to prevent unnecessary suffering and unwanted extreme measures to prolong life. However, it cannot address every possible medical scenario, which is why naming a healthcare agent is also crucial.

HIPAA Release

The Health Insurance Portability and Accountability Act (HIPAA) protects patient privacy by limiting access to medical records and information. A properly drafted HIPAA release authorizes your named healthcare agents and loved ones to receive this protected data from doctors and medical facilities.
Without a HIPAA release, your healthcare providers could legally be prohibited from sharing details of your condition or discussing your care with designated representatives. Including this document ensures open communication during a medical crisis.

Durable Power of Attorney

By having a Healthcare Proxy, living will, and HIPAA release as part of a comprehensive plan, you ensure your wishes for medical care and end-of-life treatment are legally documented and entrusted to people you have selected to uphold them. These instruments provide invaluable peace of mind about the management of your healthcare if you cannot make decisions yourself.

Choosing Agents/ Representatives

When drafting a comprehensive incapacity plan, one of the most important decisions is selecting the right people to serve as your agents or representatives. These individuals will be entrusted with tremendous responsibility for your personal care and finances if you become incapacitated. Careful thought must go into evaluating potential candidates and their qualifications.

Powers Granted

  • Banking and investment transactions
  • Managing retirement accounts
  • Paying bills and filing taxes
  • Buying, selling, or mortgaging real estate
  • Operating a business, you own
  • Handling government benefit
  • Making gifts or transferring assets
  • Hiring professional assistance (accountants, lawyers, etc.)
You can make the POA broad and all-encompassing or limit it to certain areas based on your situation. An experienced estate planning attorney can guide you in granting the proper level of authority.
With a properly drafted durable POA for finances, you ensure someone you explicitly select, and trust will have the legal ability to properly manage your financial life if you are ever unable to do so yourself. This crucial document provides invaluable peace of mind regarding the control and protection of your assets during incapacity.

Criteria for Selecting Your Agents

Your primary qualification when you are deciding who you want to name as an agent should be unwavering trust in their integrity, judgment, and commitment to uphold your wishes.

Your ideal candidate should have strong decision-making abilities, organizational skills, and be able to advocate on your behalf in difficult situations.

Many people choose close family members like a spouse, adult child or sibling. Relatives are not obligatory choices – a very close friend, spiritual advisor or professional fiduciary could also be well-suited if they deeply understand your values and preferences.
It’s wise to name at least one successor agent in case your primary choice is unable or unwilling to serve when needed. Geographical proximity can also be a consideration, especially for healthcare decisions requiring quick actions.
Here is a link to the American Bar Association’s Consumer’s Toolkit for Health Care Advance Planning:

Duties and Responsibilities of Agents

The roles and responsibilities granted to your named agents will depend on the legal instrument and type of authority granted. In general:
Financial Agents (under a durable power of attorney) are empowered to conduct financial transactions on your behalf. This includes managing investments, paying bills, filing taxes, buying/selling property and making business decisions if you own a company.
Healthcare Agents (under a durable POA for healthcare) can make medical decisions aligned with your preferences. This includes consenting to treatments, transferring you to care facilities, accessing medical records and even deciding to continue or discontinue life-sustaining measures.

Trustees (if you have a revocable living trust) are fiduciaries obligated to administer and distribute trust assets according to the trust document’s terms for your benefit.

Guardians/Conservators (named in your will) can be appointed by courts to manage your personal care and/or finances if you become incapacitated without a durable POA or trust in place.

Potential Conflicts of Interest

Even among close family members, the potential for conflicts of interest exists when one person is granted authority over another’s affairs. For example, there could be disagreements between your children regarding medical decisions or suspicions about financial mismanagement by an agent.
Having an open conversation with your agents is super important , getting their commitment, and clearly documenting your expectations in legal instruments can help prevent conflicts. Some people choose to name an impartial third-party professional fiduciary rather than a family member.
Proper vetting and selection of trusted agents is vital to ensuring your interests are protected according to your values and priorities during incapacity. With the right representatives in place, you can have peace of mind that your affairs will be capably managed exactly as you’d want if you cannot make decisions for yourself.

Long-Term Care Planning

As we age, the likelihood of needing some form of long-term care increases substantially. Planning for this potential need is crucial to protect your assets and ensure you can access quality care aligned with your wishes.

Evaluating Long-Term Care Needs and Costs

The first step is candidly assessing your individual risk factors and estimating future long-term care costs. This evaluation should consider:

  • Your current age and life expectancy
  • Family health history and existing medical conditions
  • Likelihood of requiring home care, assisted living or nursing home
  • Projected costs in your area for different care settings
  • Availability of potential family caregivers
Even for a healthy 65-year-old, the U.S. Department of Health estimates a 70% risk of needing some long-term care services before passing away. With such a high probability of requiring long-term care, even relatively healthy seniors face daunting costs.
The average annual cost for a semiprivate room in nursing homes is over $100,000. There’s a good chance that will increase by the time you or someone you love needs it.

High price tags combined with the likelihood of requiring long-term care make strategic estate planning a crucial step to avoid depleting your life savings on these expenses.

Medicaid Planning Strategies

If your assets are modest, Medicaid is likely your primary payer for long-term care. However, strict income and asset rules must be followed to qualify.

Proper Medicaid planning can help protect your home and life savings from being completely depleted by care costs.

You might include strategies like establishing an irrevocable income-only trust, making specific exempt transfers, or converting assets to Medicaid-compliant annuities. With the help of an estate planning attorney, there are other strategies you can look into as well.

However, there are look-back periods and penalties for transferring assets improperly before applying, so advanced planning is essential. 

Long-Term Care Insurance Options

For those who can afford it, long-term care insurance provides an option to cover future care costs while safeguarding assets for spouses and heirs. Traditional policies provide comprehensive coverage but can be expensive depending on age, health status and benefits selected.
Hybrid life insurance policies with accelerated long-term care riders are an alternative worth considering. These allow you to access the death benefit while alive to cover qualifying long-term care expenses if needed. Any remaining benefit is still paid out to beneficiaries after death.
No matter your current age or net worth, incorporating long-term care into your estate and retirement planning is vital. With costs rising and the burden increasingly shifting to individuals, developing a strategy to pay for quality care can protect your independence and life savings.

Disadvantages of Court-Appointed Guardians

In Massachusetts, having a court appoint a guardian or conservator to manage your affairs if you are incapacitated comes with several disadvantages:

  • Court costs like filing fees can quickly exceed $1,000
  • Court-appointed guardians may not have the same understanding of your values, wishes and best interests as someone you pre-select.
  • The process can also be expensive, public, and create family conflicts.
The 5 Legal Documents Every Parent Must Have

Secure Your future with a plan

How Proper Incapacity Planning Avoids Court

Executing key legal documents, like a durable power of attorney and revocable Living Trust, allows you to name people you trust to step in if incapacitated, rather than the court. Below are some benefits of proper incapacity planning.
  • Proper incapacity planning allows you to nominate people you trust to carry out your wishes if you become incapacitated. It safeguards your independence, dignity, and finances during a vulnerable time.
  • Writing a will and naming the special needs trust as the beneficiary, rather than your child directly, protects their access to public assistance programs.
  • With a properly drafted durable POA for finances, you ensure someone you explicitly select, and trust will have the legal ability to properly manage your financial life if you are ever unable to do so yourself.
By proactively establishing an incapacity plan, you can avoid the disadvantages of court intervention and having strangers make decisions about your care and assets against your wishes. We can’t emphasize enough how important it is to work with an experienced estate planning attorney to properly draft and execute these crucial legal instruments.

Reviewing and Updating Plans

Specific examples of life changes that should trigger an estate plan review are covered, such as:
  • Marriage or divorce
  • Birth or adoption of a child
  • Child becoming an adult
  • Death of a spouse, child, or other beneficiary
  • Inheritance or significant change in assets
  • Moving to a new state
  • Changes in tax laws or Medicaid regulations
Estate planning should be viewed as an ongoing process rather than a one-time event. You can keep your estate plan current through regular reviews and updates with your attorney. Having a qualified estate planning attorney conduct periodic reviews ensures your plan accurately reflects your latest wishes and accounts for any relevant personal or legal changes that have occurred.

Don’t leave your future to chance. You can start to take control by scheduling a call with our firm. We’ll guide you through creating the essential legal documents like a durable power of attorney, living will, and revocable trust to ensure your wishes are carried out if you become incapacitated. Protect your independence, dignity and assets by creating your incapacity plan.
As a parent, you may have questions about what you really need in place to protect your kids, your family, your assets, and yourself. From guardians and trusts to wills and health care documents, it can be hard to know where to start. Read on for answers to some of the most common estate planning questions we hear from parents.

Question 1: What is an estate plan?

When people hear the word estate, they often imagine mansions or large investments, but your estate is simply everything you own: your home, savings, personal belongings, and, most importantly, the people you want to protect.

Estate planning is about making thoughtful decisions ahead of time. It allows you to decide who would care for your children, who would make financial or medical decisions if you couldn’t, and how you want your assets managed and distributed.

Whether you’re just starting your career, growing your family, or planning for retirement, an estate plan gives you the opportunity to make those decisions yourself rather than leaving them to default state laws.

Question 2: Do I really need an estate plan if I’m young and healthy?

Even if you’re young and healthy, estate planning matters because life can change in an instant.

With a plan, you name guardians and decision-makers. Without one, many of those decisions may be left to the court or determined by state law. For example, if both parents are unable to care for their children and no guardian has been named, a court will appoint one.

A thoughtful plan can protect your family’s future, provide guidance, and help ensure your children’s inheritance is handled the way you intend.

Online forms and AI tools can be useful for general education, but they can’t provide legal advice or tailor a plan to your needs. An experienced estate planning attorney can help create a plan that’s customized, complies with state law, and is designed to hold up legally when your family needs it most.

Question 3: What documents are included in an estate plan?

A comprehensive estate plan includes several key documents that work together to protect your family.

A Will lets you name guardians for your minor children and direct how your assets are distributed.

A Revocable Living Trust can help avoid probate and provide more control over how assets are managed and distributed.

A Durable Financial Power of Attorney allows someone you trust to manage your financial affairs if you become incapacitated.

A Health Care Proxy allows you to appoint someone to make medical decisions on your behalf if you’re unable to do so.

A HIPAA Authorization gives the people you choose permission to access your medical information when needed.

The right combination of documents depends on your stage of life and your family’s unique needs.

Question 4: Do I need a will, a trust, or both?

This is one of the most common questions parents ask, and the answer depends on your goals.

A will allows you to name guardians for your minor children and direct how your assets are distributed.

A revocable living trust is often used alongside a will. It can help avoid probate, provide privacy, and give you more flexibility in how assets are managed and distributed.

For parents of young children, one of the biggest advantages of a trust is the control it provides. A trust lets you decide when and how your children receive their inheritance rather than having assets become available when they reach legal adulthood. Without that structure, significant assets like a home or investments may become available at a much younger age than most parents feel is wise. A trust also allows you to appoint someone you trust to manage those assets until your children reach the ages or milestones you choose.

For many families, the right solution includes both a will and a trust. It depends on factors like home ownership, the age of your children, and whether you want to avoid probate or set conditions for an inheritance.

Often, the better question isn’t “Do I need a will or a trust?” but “What do I want my plan to accomplish for my family?”

Question 5: How much does estate planning cost?

The cost of estate planning can vary widely depending on your family’s unique situation, goals, and the complexity of the plan.

The most important question isn’t simply what it costs, but what level of planning will best protect your family.

Once an attorney understands your goals and your situation, they can recommend the right approach and explain the fees up front.

Question 6: What happens if I don’t have an estate plan?

There is always a plan. It just may not be the one you would have chosen.

If you don’t create an estate plan, Massachusetts law provides a default plan for many important decisions. Those laws are meant to provide a framework, but they can’t account for your family’s unique needs or your preferences.

Without a plan, a court may need to appoint guardians for your minor children. Assets will be distributed according to state law, and your loved ones may experience unnecessary delays and additional stress.

Creating a plan allows you, not the state, to make those important decisions and provides clear guidance when your family needs it most.

Question 7: How do I choose a guardian for my children?

Choosing a guardian is one of the most important decisions parents make, and it can also be one of the toughest.

Many families struggle to find the one “perfect” person. At our firm, we help parents think through the decision and identify the best fit for their family. We’ll discuss questions you may not have considered, explore different scenarios, and help you make a decision that reflects your values and gives you confidence in your plan.

Thoughtful estate planning also allows you to clearly document your wishes. In some situations, parents have strong feelings about people they do not want serving as guardians. Clearly expressing those preferences in your legal plan can provide important guidance and help reduce uncertainty if difficult decisions ever need to be made.

Remember, naming a guardian isn’t permanent. As your children grow and circumstances change, your plan can be updated to reflect your family’s evolving needs.

Question 8: What happens if I don’t name a guardian?

If both parents are unable to care for their children and no guardian has been named, a court will appoint someone.

The court’s responsibility is to act in the child’s best interests, but without your guidance, the court could appoint someone you would not have chosen.

By naming a guardian, you provide the court with important guidance about who you believe is best suited to raise your children.

Question 9: When should I update my estate plan?

Estate planning isn’t something you do once and forget. Your plan should grow and change as your life does.

It’s a good idea to review your estate plan after major life events, including:

  • Getting married or divorced

  • The birth or adoption of a child

  • When your children become legal adults

  • Buying or selling a home

  • Receiving a significant inheritance

  • Starting or selling a business

  • A significant change in your financial situation

  • The death or incapacity of someone named in your plan, such as a guardian, trustee, executor, or agent under your power of attorney

  • Moving to another state

  • If your child is diagnosed with special needs, or if their diagnosis, abilities, level of independence, or long-term care needs change over time

  • Every three to five years, even if nothing major has changed

At our firm, estate planning is an ongoing relationship, not a one-time transaction. As your family grows and life changes, we’ll help you review and update your plan so it continues to reflect your wishes and protect the people you love.

Question 10: Can I create my estate plan using AI or online forms?

AI tools and online forms can be helpful for learning basic concepts or organizing your thoughts, but they can’t give legal advice or evaluate your family’s unique situation.

An estate plan is more than a set of forms. It’s a coordinated legal strategy designed around your specific goals and family dynamics.

If key issues aren’t addressed, certain decisions may default to state law, which can lead to unintended results.

Working with a qualified estate planning attorney who works with young families every day helps ensure your plan is tailored to your family’s needs and wishes. Rather than a one-time transaction, you’ll have a trusted advisor who can help keep your plan current as life changes.

Question 11: How do I get started?

Getting started is often easier than people expect.

The first step is scheduling a complimentary 15-minute call with our Client Services Coordinator.

You don’t need to have all the answers before you reach out. You don’t need to know exactly who you’d choose as guardians or what documents you need. That’s what we’re here to help with.

During that call, we’ll learn a little about your family, answer your initial questions, explain what to expect, and help determine the next best step.

If it makes sense to move forward, we’ll schedule a planning session with one of our attorneys, where we’ll talk through your goals, explain your options in plain language, and help you feel confident about the path forward.

Our goal is to make estate planning approachable, understandable, and personal so you can move forward with confidence, knowing your family is protected.

Question 12: What can I expect during my planning session?

Your planning session is a conversation, not a presentation.

We’ll take time to get to know you, listen to your goals, and answer your questions. We’ll walk you through decisions you may not have thought about, such as guardianship and how and when assets should pass to your children.

By the end of your planning session, you’ll have a clear understanding of your options, what we recommend, why we recommend it, and what the next steps look like.

Our goal isn’t simply to create legal documents. It’s to help you build a thoughtful estate plan that reflects your wishes and protects the people you love.

Question 13: How long will my estate plan take to complete?

Creating your estate plan begins with your planning session, and we ask clients to reserve about 90 minutes so we can truly understand your family and your goals.

During the first part of your planning session, we’ll get to know you, answer your questions, explore your wishes, and discuss what’s most important to you. We’ll explain your options in plain language and recommend the level of planning that’s right for your family’s unique situation.

If you decide to move forward with our firm, the second part of the planning session is spent beginning to design your estate plan. Together, we’ll map out the important decisions and gather the information needed to prepare documents that reflect your wishes and protect your family.

It takes about four weeks from your planning session to signing your estate planning documents. A lot will depend on how quickly you’re able to finalize your decisions. It’s important to remember that nothing is legal until it is signed, so we move you to your signing meeting as quickly as possible.

We’ll be with you every step of the way, keeping you informed so you’ll always know what to expect.

Ready to protect your family? Schedule a complimentary 15-minute call with our Client Services Coordinator to get started. Let’s chat. 

Parents Estate Planning Logo

The Parents Estate Planning Law Firm, PC

At The Parents Estate Planning Law Firm, we answer your questions at your convenience; we stay in frequent communication; and we meet to discuss changes in life circumstances and in the law to ensure that your assets are protected.

Share This:

Schedule a
Planning Session

Free Monthly Newsletter

Get valuable information delivered to your inbox each month!

Special Reports

Image of Kids Protection Planning Guide

Kids Protection Planning Guide®

Emptying the Nest

Emptying the Nest: 8 Ways Your Estate Plan Changes When Your Children Become Adults